

Published: 8 October 2026 | VaultStreet Advisors | Unlisted & Pre-IPO Shares
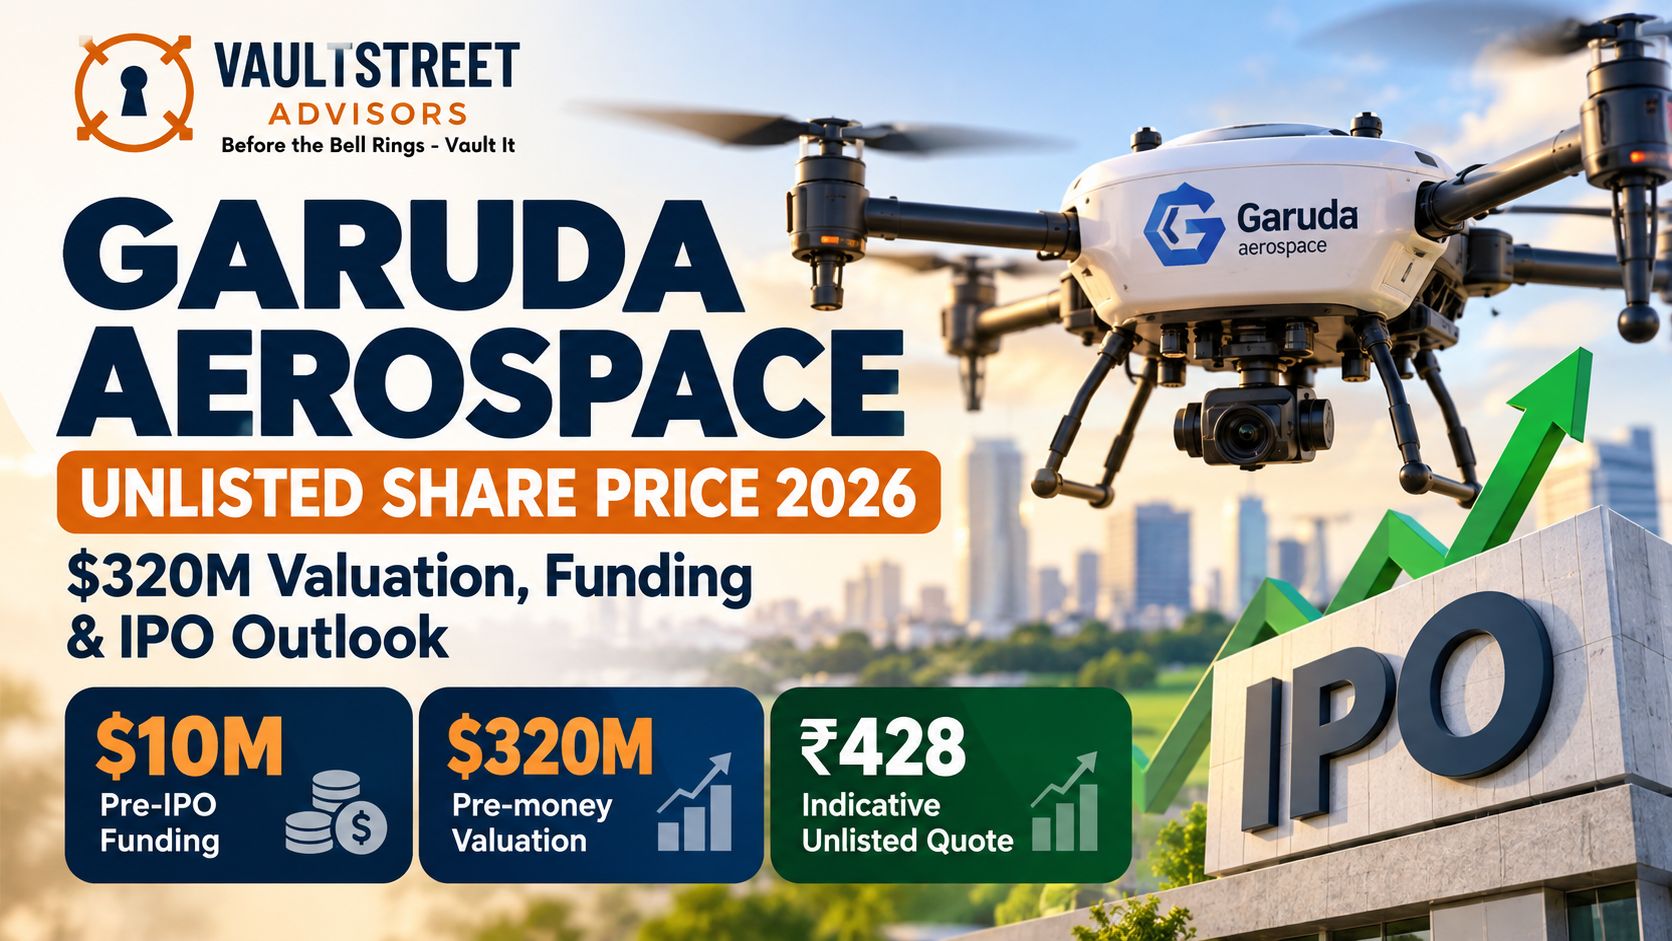
Garuda Aerospace is attracting renewed attention in India’s unlisted share market following reports of a $10 million pre-IPO funding round at a $320 million pre-money valuation.
For investors tracking Garuda Aerospace unlisted shares, the development raises an important question: Does the latest institutional valuation justify the price being quoted in the secondary market?
Indicative third-party quotations around ₹428–431 per share were reported for 7 October 2026. However, a private funding valuation and an unlisted-market quotation cannot be directly compared without understanding the company’s share capital, funding terms and applicable corporate actions.
With Garuda Aerospace reportedly targeting an IPO in the first quarter of 2027, investors also need to examine its financial performance, operating cash flow, stock split and potential listing risks.
This analysis by VaultStreet Advisors examines the available information, distinguishes confirmed disclosures from reported developments and explains what investors should monitor.
1. Garuda Aerospace Unlisted Shares: Latest Developments
| Particulars | Position as of 8 October 2026 |
|---|---|
| Company | Garuda Aerospace Limited |
| Industry | Drone manufacturing and drone-related services |
| Indicative unlisted share price | ₹428–431 per share, reported for 7 October 2026 |
| Reported pre-IPO funding | Approximately $10 million (₹96 crore) |
| Reported pre-money valuation | $320 million |
| Illustrative post-money valuation | $330 million |
| Reported funding participants | Motherson family office and Aditum Investment Group |
| Pre-filed DRHP | Dated 29 March 2026 |
| Official filing announcement | 31 March 2026 |
| Reported SEBI observations | 5 August 2026 |
| Expected IPO | First quarter of 2027, according to media reports |
| Confirmed IPO price band | Not announced |
| Confirmed listing date | Not announced |
Important: The funding valuation and IPO target are based on financial-media reporting. The indicative share price is a historical third-party market reference, not a confirmed executable quotation from VaultStreet Advisors.
2. Garuda Aerospace Raises $10 Million Before Its Proposed IPO
According to The Economic Times, Garuda Aerospace raised approximately $10 million in pre-IPO funding at a reported pre-money valuation of $320 million.
The report identified the Motherson family office and Dubai-based Aditum Investment Group as funding participants.
The development is significant because Garuda Aerospace is preparing for a potential transition from private ownership to the public equity market.
Pre-IPO capital can help a company expand manufacturing capacity, invest in technology, strengthen working capital and support future business requirements.
However, institutional funding does not automatically establish the fair value of shares available to retail buyers in the unlisted market.
Institutional investors may negotiate specific rights, protections or other transaction terms that differ from those available to ordinary secondary-market participants.
The detailed security structure and contractual terms of this funding round have not been established in the public sources reviewed.
What Does the $320 Million Valuation Mean?
A pre-money valuation represents the negotiated equity value of a company before new investment capital is added.
Assuming the entire reported $10 million was invested through newly issued ordinary equity, the simplified calculation would be:
| Valuation component | Amount |
|---|---|
| Pre-money valuation | $320 million |
| New funding | $10 million |
| Illustrative post-money valuation | $330 million |
| Illustrative new investor ownership | Approximately 3.03% |
The ownership percentage is calculated by dividing $10 million by $330 million.
This is an illustration rather than confirmation of the investors’ actual ownership.
Does the Funding Valuation Make Garuda Aerospace Unlisted Shares Attractive?
Not necessarily.
To calculate an implied value per share, investors need reliable information about the company’s fully diluted equity capital.
The simplified formula is:
Implied value per share = Equity valuation ÷ Fully diluted number of shares
The calculation may also require adjustments for convertible securities, employee stock options, preferential rights and other transaction conditions.
Without these details, it would be misleading to claim that an indicative ₹428 quotation represents a discount or premium to the institutional funding valuation.
VaultStreet Advisors has examined this issue in its article on why unlisted share prices and eventual IPO prices can differ.
3. Garuda Aerospace Unlisted Share Price in October 2026
Indicative third-party dealer quotations around ₹428–431 per share were reported for 7 October 2026.
These figures should be treated as historical market indications rather than confirmed transaction prices. Current availability, quantities and executable prices require separate verification.
Unlike actively traded listed securities, unlisted shares do not have a continuously visible centralised exchange order book.
Prices may differ depending on the dealer, quantity, buyer demand, seller availability, settlement arrangements and transaction timing.
Why Do Unlisted Share Prices Differ Between Dealers?
An unlisted-share quotation may reflect the terms offered by a particular seller rather than a broad, liquid market.
Investors should distinguish between an indicative website quotation, a confirmed offer for a specified quantity and the actual price agreed between a buyer and seller.
The eventual IPO issue price and post-listing market price are separate matters.
An indicative unlisted share price does not guarantee liquidity, execution or future returns.
For current indicative Garuda Aerospace share availability and settlement information, readers can contact VaultStreet Advisors.
4. Garuda Aerospace Financial Performance: Why Cash Flow Matters
Garuda Aerospace’s financial performance deserves careful examination as the company approaches a potential IPO.
The company maintains an official annual-report archive, including financial disclosures for FY2024–25 and FY2025–26.
Revenue growth and accounting profitability are important indicators, but they do not necessarily mean a company is generating sufficient operating cash.
A business can report profits while consuming cash because customers have not yet paid outstanding invoices, inventories are increasing or other working-capital requirements are absorbing funds.
Revenue, Profit and Operating Cash Flow Are Different Measures
Revenue represents income recognised from business activities under applicable accounting standards.
Profit after tax represents accounting earnings after expenses and taxes.
Operating cash flow reflects cash generated or consumed through operating activities.
These measures can move in different directions.
Published secondary financial analyses of Garuda Aerospace’s FY26 results have raised questions about negative operating cash flow and receivables. However, the detailed numerical comparisons have not been independently reconciled against the original audited financial statements for this article.
Accordingly, investors should rely on the company’s official financial disclosures for precise figures and ratios.
Why Are Trade Receivables Important?
Trade receivables represent amounts owed by customers.
A growing receivables balance may accompany business expansion, but investors need to understand whether cash collections are keeping pace with reported sales.
Important questions include:
- How much reported revenue has converted into cash?
- What proportion of receivables is overdue?
- Are collections concentrated among a limited number of customers?
- How much working capital is required to support new orders?
- Will fresh funding primarily support expansion or existing liquidity requirements?
These questions are especially relevant when evaluating a growing manufacturing business before an IPO.
The ability to convert reported earnings into sustainable cash generation can be as important as revenue growth itself.
5. Garuda Aerospace Stock Split: Why Historical Share Prices Need Adjustment
Garuda Aerospace announced a subdivision of equity shares from a face value of ₹10 to ₹2.
This represents a five-for-one share split.
The company’s official March 2026 IPO pre-filing announcement identifies equity shares with a face value of ₹2 each.
Consider the following illustration:
| Particulars | Before subdivision | After subdivision |
|---|---|---|
| Shares held | 100 | 500 |
| Illustrative price per share | ₹2,000 | ₹400 |
| Total holding value | ₹2,00,000 | ₹2,00,000 |
The illustration assumes no change in the company’s overall equity valuation.
A stock split increases the number of shares and proportionately adjusts the theoretical per-share value. It does not automatically increase shareholder wealth.
Why Does This Matter to Unlisted Shareholders?
Historical quotations based on ₹10 face-value shares cannot be compared directly with newer quotations for ₹2 face-value shares without appropriate adjustment.
Investors should also verify the current ISIN, security description, applicable corporate actions and demat details before completing an off-market transaction.
6. Garuda Aerospace IPO 2027: What Is Officially Confirmed?
Garuda Aerospace has formally initiated the IPO process.
An official announcement dated 31 March 2026 confirms a pre-filed Draft Red Herring Prospectus dated 29 March 2026.
The announcement relates to the proposed IPO of ₹2 face-value equity shares on the main board of the stock exchanges.
Importantly, filing the documents does not guarantee that the IPO will ultimately proceed.
Garuda Aerospace IPO Timeline
| Date or period | Development | Status |
|---|---|---|
| 29 March 2026 | Pre-filed DRHP dated | Officially documented |
| 31 March 2026 | Public announcement of filing | Officially documented |
| 5 August 2026 | SEBI observations reportedly issued | Financial-media reporting |
| 7 October 2026 | Approximately $10 million funding reported | Financial-media reporting |
| Q1 2027 | Targeted IPO period | Reported expectation |
| IPO price band | Not announced | Pending |
| Listing date | Not announced | Pending |
Financial-media reports indicate that Garuda Aerospace received SEBI observations on 5 August 2026 and is targeting an IPO in the first quarter of 2027.
Investors can monitor the company’s official IPO disclosures for updated documentation.
Does Receiving SEBI Observations Guarantee an IPO?
No.
Regulatory observations represent an important procedural milestone, but they do not guarantee that an issue will open on a particular date or at a particular valuation.
Market conditions, updated financial information, regulatory requirements and company decisions can affect the eventual timetable.
As of 8 October 2026, a final IPO price band and listing date had not been established in the sources reviewed.
7. Could Garuda Aerospace’s IPO Price Differ From Its Unlisted Share Price?
Yes, potentially by a significant amount.
An institutional funding valuation, a secondary-market quotation and an IPO issue price are determined through different processes.
The eventual public-market valuation may depend on several factors:
- Revenue growth and operating profitability.
- Cash-flow generation and working-capital requirements.
- Borrowings and capital expenditure.
- Order execution and customer concentration.
- Competition within the drone industry.
- Fully diluted equity capital.
- IPO issue structure and shareholder dilution.
- Broader equity-market conditions.
For investors, the distinction is important.
A successful IPO does not necessarily mean that every pre-IPO shareholder will earn a positive return.
The entry valuation matters.
A company can have strong growth prospects while its shares are priced at a level that leaves limited room for disappointing financial results or changing market sentiment.
8. Garuda Aerospace and India’s Growing Drone Industry
Garuda Aerospace operates within India’s developing drone manufacturing and services ecosystem.
The industry includes businesses involved in agricultural applications, industrial inspection, mapping, surveillance, defence-related technologies and other commercial uses.
However, companies within the same industry can have very different business models.
A manufacturer of complete drone platforms may have different margins, capital requirements and competitive advantages from a supplier of propulsion systems, sensors, batteries or navigation components.
VaultStreet Advisors has examined these distinctions in its article on India’s listed and unlisted drone-component manufacturers.
Readers researching other private-market companies in this sector can also explore the Gamma Rotors unlisted share company profile.
These companies should not be assumed to have comparable valuations merely because they participate in the same industry.
What Could Influence Garuda Aerospace’s Future Growth?
Potential factors include wider commercial drone adoption, domestic manufacturing capabilities, agricultural applications, industrial demand and specialised technology development.
However, growth in an industry does not guarantee that every participating company will achieve its projected revenue, profitability or market share.
Investors must distinguish between the prospects of a sector and the financial performance of an individual business.
9. Key Risks Before Buying Garuda Aerospace Unlisted Shares
Liquidity Risk
Unlisted shares may be difficult to sell at the desired price or within a particular timeframe.
Valuation Risk
Secondary-market quotations may already reflect optimistic expectations about future growth or an IPO.
IPO Timing Risk
A proposed IPO may be delayed, revised or withdrawn.
Financial Risk
Business expansion can require substantial working capital, capital expenditure and external funding. Investors should examine audited financial statements and cash-flow disclosures.
Dilution Risk
Future equity issuance, convertible instruments or employee stock options may affect ownership percentages and per-share value.
Lock-In and Transfer Restrictions
Certain pre-IPO holdings may be subject to applicable lock-in provisions or other transfer restrictions.
Investors should verify the requirements relevant to their specific shares.
Settlement Risk
Off-market transactions require correct security identification, documentation, demat details and payment arrangements.
Buyers should verify transaction terms and counterparties before transferring funds.
10. What Should Existing Garuda Aerospace Shareholders Monitor?
Existing shareholders should pay attention to four important areas.
Financial performance: Updated revenue, profitability, operating cash flow, receivables, borrowings and capital expenditure.
Corporate actions: Changes in share capital, stock subdivisions, convertible securities and shareholder rights.
IPO developments: Updated offer documents, issue structure, valuation, timetable and applicable lock-in requirements.
Secondary-market liquidity: Actual transaction availability, dealer quotations, bid-offer differences and settlement terms.
A rising indicative quotation does not necessarily mean a shareholder can immediately sell a large holding at that price.
Similarly, an IPO announcement does not guarantee that every existing shareholder can sell immediately after listing.
11. Frequently Asked Questions
What is Garuda Aerospace’s unlisted share price in October 2026?
Indicative third-party quotations around ₹428–431 per share were reported for 7 October 2026. These are historical market indications, not confirmed executable prices.
What is Garuda Aerospace’s latest reported valuation?
The Economic Times reported a $320 million pre-money valuation associated with approximately $10 million of pre-IPO funding in October 2026.
When is Garuda Aerospace expected to launch its IPO?
Financial-media reports indicate a first-quarter 2027 target. The final issue opening date, price band and listing date have not been confirmed.
Has Garuda Aerospace filed its IPO documents?
Yes. An official announcement dated 31 March 2026 confirms a pre-filed DRHP dated 29 March 2026.
Has Garuda Aerospace received SEBI observations?
Financial-media reports indicate that SEBI issued observations on 5 August 2026. This does not guarantee a particular IPO date or valuation.
Has Garuda Aerospace announced a stock split?
Yes. The company announced a subdivision from ₹10 to ₹2 face value. Its March 2026 IPO announcement refers to ₹2 face-value equity shares.
Why is operating cash flow important for Garuda Aerospace?
Operating cash flow helps investors understand whether reported business activity is generating cash. Working-capital requirements and customer collections are important considerations for a growing manufacturing company.
Can Garuda Aerospace unlisted shares be purchased before the IPO?
Transactions may be possible where shares are available and legally transferable, subject to documentation, applicable requirements and settlement terms.
Will Garuda Aerospace shares deliver listing gains?
There is no guarantee. The outcome will depend on the acquisition price, eventual IPO valuation, company fundamentals and market conditions.
How can investors enquire about Garuda Aerospace unlisted shares?
Investors can contact VaultStreet Advisors to enquire about indicative availability, prevailing quotations, documentation and settlement requirements.
12. Conclusion: The Funding Headline Is Only Part of the Story
Garuda Aerospace’s reported $10 million funding round represents an important development ahead of its proposed public listing.
The reported $320 million valuation provides a recent institutional reference point, while interest in the company’s unlisted shares reflects expectations surrounding India’s drone industry and the potential IPO.
However, investors should not equate institutional funding with an assured fair value for secondary-market shares.
The company’s fully diluted capital structure, financial performance, cash generation, IPO terms and entry valuation remain essential considerations.
For Garuda Aerospace shareholders, the real question is not simply whether the IPO happens in 2027. It is whether the eventual public-market valuation justifies the price paid before listing.
At VaultStreet Advisors, our objective is to help market participants understand unlisted-share opportunities, indicative quotations, documentation and transaction processes while recognising the associated risks.
Connect With VaultStreet Advisors
Interested in checking the indicative availability of Garuda Aerospace unlisted shares or understanding the transaction process?
Website: www.vaultstreet.in
Unlisted Share Enquiries: +91 91379 69859
Exclusive WhatsApp Community: Message +91 99875 53455 to request access to our exclusive WhatsApp community for daily prices, opportunities and market updates.
For listed equity and derivatives, connect with Riddhi Siddhi Share Brokers for Assisted Trading Services and Trade Execution Support.
Explore the Riddhi Siddhi Share Brokers services page for more information.
Disclaimer
VaultStreet Advisors is a boutique platform focused on facilitating unlisted share transactions. We do not provide investment advisory services or portfolio recommendations. All investments are subject to market risks. Please consult your financial advisor before investing.
This article is for educational and informational purposes only. It does not constitute an investment recommendation, offer or solicitation to buy or sell securities. Reported funding valuations and IPO expectations are subject to change. Indicative unlisted share prices are not guaranteed executable quotations. Unlisted securities carry liquidity, valuation, regulatory, settlement and capital-loss risks. Readers should independently verify relevant company disclosures and consult qualified financial, legal and tax professionals before making investment decisions.