

For many investors, the journey of an unlisted share appears straightforward:
Buy before the IPO → wait for listing → exit.
But one of India’s most closely watched private-company ownership situations is showing why the unlisted market can be far more complex.
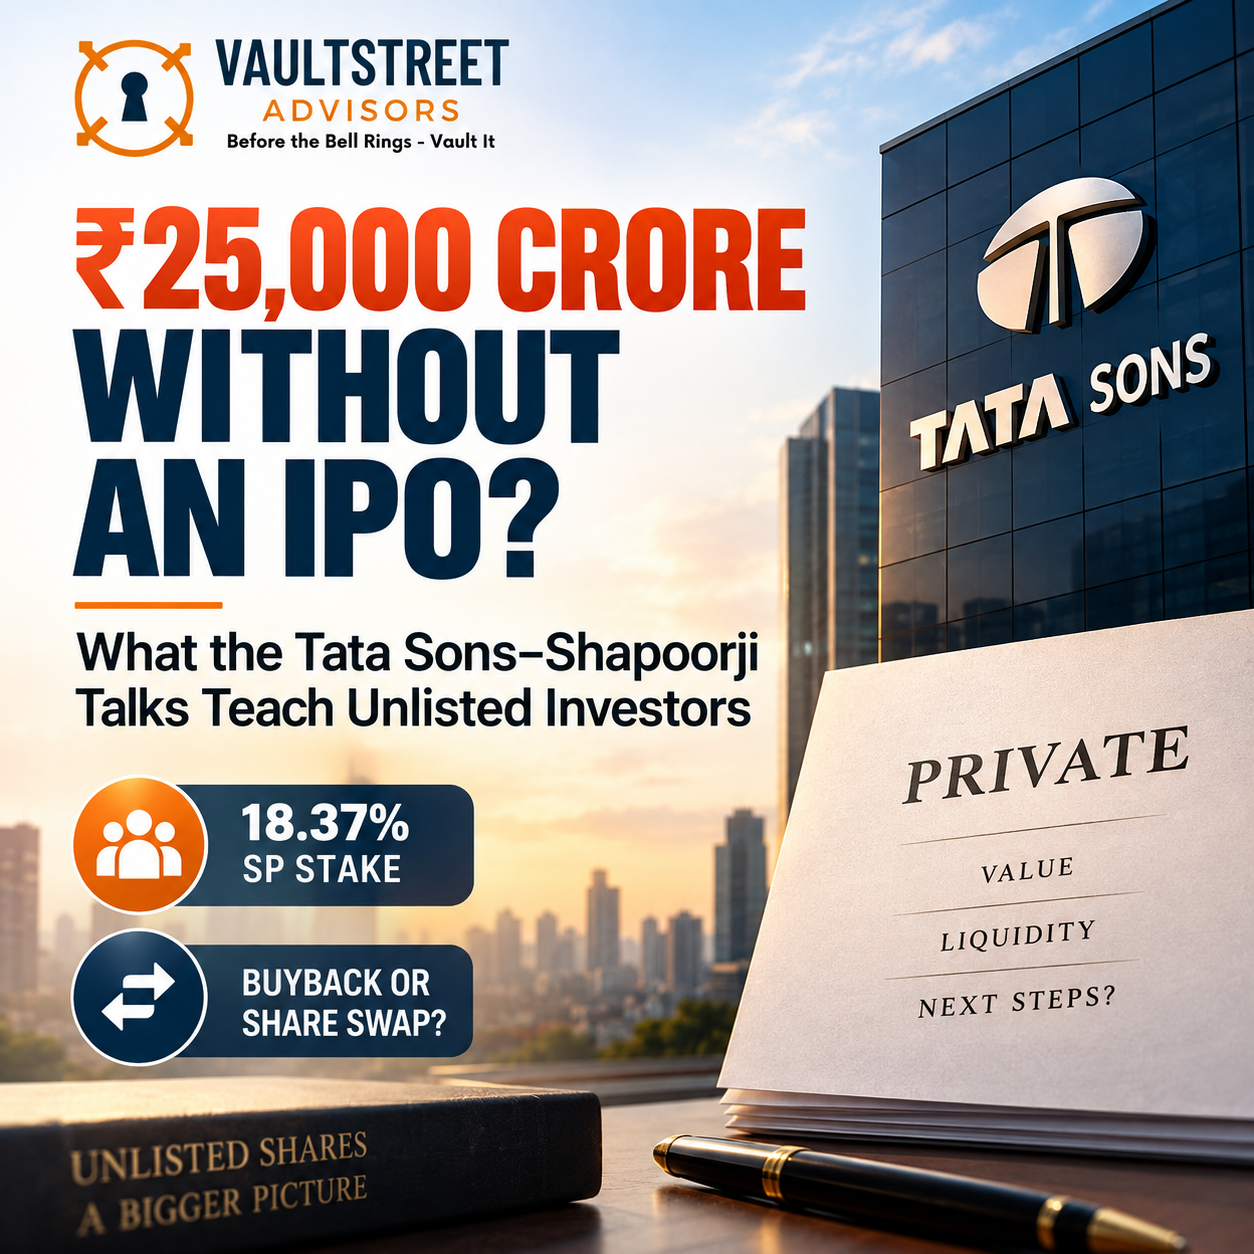
On 12 September 2026, The Economic Times reported that Shapoorji Pallonji (SP) Group chairman Shapoor Mistry has sought around ₹25,000 crore from Tata Sons over the next 24 months through monetisation of part of the SP Group’s holding in Tata Sons.
SP Group owns an estimated 18.37% of unlisted Tata Sons and has reportedly been exploring ways to monetise approximately 7% of its holding.
What makes the development particularly interesting is that the potential solutions being discussed do not necessarily require Tata Sons to launch an IPO.
A partial buyback, a share swap involving listed Tata companies or another negotiated structure could potentially provide liquidity to a major shareholder while Tata Sons remains private.
And that raises a fascinating question for anyone investing in unlisted shares:
Does a Valuable Unlisted Company Actually Need an IPO to Create Liquidity?
The answer is no.
And the Tata Sons–Shapoorji situation offers an unusually powerful real-world lesson in how liquidity, valuation and exits can work in private companies.
What Exactly Is Happening Between Tata Sons and Shapoorji Pallonji?
According to reports on 12 September, the SP Group has proposed raising approximately ₹25,000 crore over two years against part of its Tata Sons holding.
Importantly, no final transaction has been announced or agreed.
The discussions reportedly involve several important issues, including:
- Valuation
- Transaction structure
- Funding mechanism
- Quantum of shares involved
- Timing of monetisation
One structure reportedly discussed earlier was a share swap, under which SP Group could receive shares of listed Tata companies in return for part of its Tata Sons stake.
Another reported possibility involves a buyback, which could potentially provide SP Group with cash while allowing Tata Sons to continue as a private company.
That distinction is extremely important.
The story is not:
“Tata Sons is doing a ₹25,000 crore buyback.”
The more accurate position is:
A potential stake-monetisation arrangement involving approximately ₹25,000 crore has reportedly been proposed and is under discussion. No final agreement has been announced.
For investors, the interesting part is not merely the size of the number.
It is the mechanism.
Why Would SP Group Want Liquidity?
The SP Group’s Tata Sons holding is an enormously valuable asset, but an important characteristic of that asset is often overlooked:
Tata Sons is unlisted.
An investor owning shares of a listed Tata company can normally sell those shares through the stock exchange.
A shareholder in Tata Sons cannot simply open a trading application and sell billions of rupees worth of shares on NSE or BSE.
That means an asset can be extremely valuable and still face a liquidity challenge.
The SP Group has also undertaken substantial refinancing backed by its Tata Sons holding, further demonstrating how large private-company stakes can be used to generate liquidity without an outright sale.
This highlights one of the most important distinctions every unlisted investor should understand:
Value and Liquidity Are Not the Same Thing
An asset may theoretically be worth thousands of crores.
But converting that value into cash can require:
- Finding another buyer
- Arranging financing against the shares
- Negotiating with existing shareholders
- Conducting a buyback
- Exchanging the holding for another asset
- Corporate restructuring
- Or eventually accessing the public markets
This difference between valuation and liquidity sits at the heart of unlisted investing.
For investors who are new to this market, VaultStreet Advisors’ guide on what unlisted shares are and how to invest in them safely provides a useful introduction to how this asset class works.
The Big Lesson: IPO Is Only One Route to Liquidity
Many retail investors approach unlisted shares with a single exit assumption:
“The company will eventually launch an IPO.”
But an IPO is only one possible liquidity event.
Private-company shareholders may potentially receive liquidity through several mechanisms.
1. Share Buyback
A company may buy shares from existing shareholders, subject to applicable laws, regulations and the company’s constitutional documents.
For the selling shareholder, this can convert an illiquid private holding into cash.
For the company, it can potentially restructure ownership without becoming publicly listed.
The Tata Sons discussions demonstrate why a buyback can become strategically important when a large shareholder seeks liquidity.
2. Secondary Share Sale
An existing shareholder may sell shares to another investor.
The purchaser could potentially be:
- An institutional investor
- Private equity fund
- Family office
- Strategic investor
- Another existing shareholder
- Or another eligible buyer
This is essentially how a significant part of the broader unlisted-share ecosystem functions.
Ownership changes. The company itself does not necessarily raise capital. And no IPO is required.
Investors wanting to understand this process in greater detail can read VaultStreet Advisors’ guide on how to sell unlisted shares and exit before an IPO.
3. Share Swap
Instead of receiving cash, one shareholder may exchange its holding for shares or securities in another company.
A reported proposal in the Tata Sons discussions contemplated SP Group potentially receiving a basket of listed Tata-company shares against part of its holding.
Such a structure could potentially transform an illiquid private-company asset into securities with substantially greater market liquidity.
4. Financing Against Shares
An investor may continue owning an unlisted asset while borrowing against it.
The SP Group itself provides an important example of how significant private-company stakes can be used as collateral in financing arrangements.
However:
Borrowing against shares is not equivalent to selling them.
The shareholder receives liquidity but also assumes financing obligations, including interest, repayment requirements and potentially collateral-related conditions.
5. IPO
And finally, there is the route most retail investors immediately think about:
The Initial Public Offering.
An IPO can fundamentally change the liquidity profile of a company because its shares eventually become exchange traded.
But it is neither the only potential exit route nor an assured one.
That is a concept investors should understand before purchasing any pre-IPO or unlisted share.
What About the Tata Sons IPO?
This is where the situation becomes particularly interesting.
Tata Sons has been part of a wider regulatory discussion because of its classification within the Reserve Bank of India’s scale-based regulatory framework for NBFCs.
At the same time, Tata Sons has pursued surrender of its Core Investment Company registration, creating an important regulatory question around how its status will ultimately be resolved.
Investors should therefore be careful with simplistic headlines such as:
“Tata Sons must IPO.”
or
“Tata Sons IPO cancelled.”
The more accurate position is that its regulatory status and the implications for any future listing remain a developing matter.
Meanwhile, the current SP Group discussions demonstrate something even more interesting:
A major shareholder may require liquidity independently of whether or when a public listing happens.
That creates an incentive to explore alternative structures.
₹25,000 Crore Sounds Huge — But What Does It Tell Us About Tata Sons’ Valuation?
This is where investors need to exercise caution.
A common temptation would be to take the ₹25,000 crore headline number and reverse-engineer a precise valuation for Tata Sons.
That could be misleading.
Why?
Because the final transaction structure has not been agreed.
We do not yet know precisely:
- How much stake would ultimately be monetised
- Whether the transaction would occur in one stage or several
- What valuation methodology would be used
- Whether discounts or premiums would apply
- Whether consideration would be entirely cash
- Whether there would be a share swap
- What other commercial conditions could form part of the arrangement
Therefore, the reported ₹25,000 crore should not automatically be treated as an independent market valuation of Tata Sons.
This distinction matters far beyond Tata Sons.
Unlisted Share Price Is Not the Same as Fair Value
One of the biggest mistakes investors can make in the unlisted market is assuming:
“Someone traded the share at this price, therefore this must be what the company is worth.”
Not necessarily.
Private-market prices can depend on several factors.
Transaction Size
A buyer purchasing ₹5 lakh worth of shares may receive a very different price from someone negotiating a multi-thousand-crore block.
Liquidity
A shareholder urgently requiring cash may accept terms another shareholder would reject.
Rights Attached to the Shares
Large strategic holdings can carry economic considerations very different from small minority holdings.
Transaction Structure
Cash purchases, share swaps, structured finance and buybacks cannot always be compared directly.
Negotiating Power
The identity and bargaining position of the buyer and seller can matter considerably in negotiated private-market transactions.
That is why serious unlisted investors should focus on implied company valuation, not merely the quoted price per share.
VaultStreet Advisors has discussed several of these issues in our guide to pre-IPO investment risks investors should understand before buying unlisted shares.
🔐 EXPLORE INDIA’S UNLISTED & PRE-IPO MARKET
Interested in understanding current unlisted and pre-IPO opportunities, prices and market developments?
🌐 Visit VaultStreet Advisors
📲 Message +91 99875 53455 to request access to our exclusive WhatsApp community for daily prices, opportunities and market updates.
Before the bell rings… Vault it!
Tata Sons Offers an Important Lesson for Retail Unlisted Investors
Obviously, a minority investor holding a few lakh rupees of an unlisted company is in a completely different position from SP Group holding approximately 18.37% of Tata Sons.
But the underlying principle remains relevant:
Buying Is Only Half the Investment Decision. Understanding the Exit Is the Other Half.
Before purchasing any unlisted share, investors should ask:
1. Is an IPO Genuinely Progressing?
There is a major difference between:
“The company may list someday.”
and
“The company has begun a documented IPO process.”
Investors should distinguish evidence from market speculation.
2. What If the IPO Never Happens?
This may be the most important question.
If you would not want to own the company without an IPO, your investment thesis may be based more on an anticipated event than on the underlying business.
3. Is There a Secondary Market?
Popular unlisted companies may have significant buyer interest.
Others can become extremely difficult to sell.
Liquidity can also disappear when sentiment changes.
4. What Valuation Am I Entering At?
A strong company can still be a poor investment when purchased at an excessive valuation.
VaultStreet Advisors recently explored this principle in our analysis of NSE unlisted shares before the IPO.
The central question is not simply whether a company is good.
It is:
Are you buying that company at a sensible valuation?
5. Who Could Eventually Provide Liquidity?
Possible routes might include:
- Another unlisted-market buyer
- Institutional secondary transactions
- Strategic investors
- Buybacks
- Corporate restructuring
- Acquisition
- Or an eventual IPO
Not every company will have every option.
That uncertainty forms part of the risk involved in private-market investing.
Great Company Does Not Automatically Mean Great Investment
This deserves particular emphasis.
Investors often become attracted to unlisted shares because they recognise the company name.
But:
Great Company + Wrong Valuation Can Still Equal a Poor Investment Decision.
This applies whether the company is Tata Sons, NSE or another highly sought-after private business.
Company quality matters.
Growth prospects matter.
But so do:
Entry valuation + liquidity + holding period + potential dilution + regulatory risk + exit possibilities.
That is why an investor should never buy an unlisted share purely because an IPO is expected.
Listed Markets and Unlisted Markets Work Differently
There is also an important distinction between investing before and after listing.
Once a company becomes listed on a recognised stock exchange, price discovery, liquidity and transaction mechanisms become fundamentally different from negotiated private-market transactions.
Investors interested in listed equities, IPOs and other stock-market products can explore Riddhi Siddhi Share Brokers.
Riddhi Siddhi Share Brokers operates in the listed-market ecosystem as an NSE & BSE Authorised Person of a leading broker, while VaultStreet Advisors focuses on facilitating opportunities in the unlisted and pre-IPO market.
Understanding this difference is important because an unlisted investment should not be evaluated as though it already has stock-exchange liquidity.
The Bigger Lesson: Valuable Does Not Mean Liquid
Tata Sons sits at the centre of one of India’s largest corporate groups.
Yet a shareholder owning a substantial stake can still face the fundamental private-market challenge:
How Do You Monetise an Enormously Valuable Asset When There Is No Public Market for It?
That is perhaps the most useful takeaway from this entire story.
Retail investors sometimes believe liquidity risk applies mainly to obscure private companies.
It does not.
Liquidity is a structural characteristic of unlisted ownership.
A business can be:
- Highly profitable
- Exceptionally valuable
- Strategically important
- Institutionally owned
…and still have shares that cannot be instantly converted into cash.
This is why liquidity deserves the same attention as growth and valuation when analysing an unlisted investment.
The ₹25,000 Crore Question: Could Tata Sons Remain Private?
Potentially, yes.
The reported proposal is particularly interesting precisely because it could provide SP Group with liquidity without necessarily requiring Tata Sons to become publicly listed.
But investors should not jump from possibility to conclusion.
No final transaction has been announced.
Valuation remains under discussion.
Structure remains under discussion.
The amount of stake ultimately monetised remains uncertain.
And Tata Sons’ broader regulatory position continues to evolve.
Therefore, the correct takeaway is not:
“Tata Sons will stay private.”
It is:
Private companies can sometimes create enormous shareholder liquidity without going public — and the Tata Sons–SP discussions are providing a remarkable case study of how that could happen.
What This Means for India’s Growing Unlisted Market
India’s unlisted and pre-IPO market is becoming increasingly accessible to individual investors.
But greater access should bring greater sophistication.
Too much investor attention continues to revolve around one question:
“When is the IPO?”
A better sequence of questions is:
What is the business worth?
What valuation am I paying?
How liquid is the investment?
What could create liquidity?
How long might that take?
What happens if the expected IPO is delayed or never happens?
Institutional investors tend to think about:
Business → Valuation → Risk → Holding Period → Liquidity → Exit
Retail investors purchasing unlisted shares should increasingly do the same.
The VaultStreet View
The Tata Sons–Shapoorji discussions illustrate one of the most important principles in private-market investing:
Liquidity Does Not Begin and End With an IPO.
An IPO can be a major liquidity event.
But shareholders may also create liquidity through secondary transactions, buybacks, strategic transactions, share swaps and other permitted mechanisms.
Investors should therefore avoid reducing an unlisted investment thesis to:
“IPO kab aayega?”
The better question is:
“What gives this investment value today, and what realistic routes could convert that value into liquidity tomorrow?”
At VaultStreet Advisors, we believe understanding business quality, valuation, liquidity and risk should come before chasing an IPO narrative.
For investors still learning how private markets work, explore our unlisted shares insights and opportunities for more educational content on India’s growing unlisted ecosystem.
📲 INTERESTED IN UNLISTED & PRE-IPO OPPORTUNITIES?
Don’t just wait for the IPO. Understand the opportunity before the bell rings.
🔐 Explore India’s unlisted and pre-IPO market with VaultStreet Advisors.
🌐 Website: www.vaultstreet.in
💬 Exclusive WhatsApp Community
Message +91 99875 53455 to request access to our exclusive WhatsApp community for daily prices, opportunities and market updates.
Get access to:
✓ Daily unlisted share prices
✓ New unlisted & pre-IPO opportunities
✓ Market developments
✓ IPO-related updates
✓ Educational insights on the unlisted marketBefore the bell rings… Vault it!
For listed equities, IPOs, mutual funds, derivatives, SLBM and other stock-market services, visit Riddhi Siddhi Share Brokers.
Frequently Asked Questions
Is Tata Sons Listed on NSE or BSE?
No. Tata Sons Private Limited remains an unlisted company as of 12 September 2026.
Does SP Group Own Shares in Tata Sons?
Yes. SP Group is reported to own approximately 18.37% of Tata Sons, making it the largest shareholder outside Tata Trusts.
Is Tata Sons Conducting a ₹25,000 Crore Buyback?
No completed ₹25,000 crore buyback has been announced.
Reports indicate that SP Group has sought approximately ₹25,000 crore over the next 24 months through monetisation of part of its Tata Sons stake, with a possible buyback among the structures reportedly being discussed.
How Much of Tata Sons Does SP Group Reportedly Want to Monetise?
Reports indicate SP Group has explored monetising approximately 7% of its Tata Sons holding, although the final quantum, valuation and transaction structure have not been agreed.
Will Tata Sons Launch an IPO?
There is currently no certainty regarding a Tata Sons IPO. Regulatory developments have generated considerable speculation, but investors should not treat a future listing as confirmed.
Can Shareholders in an Unlisted Company Get Liquidity Without an IPO?
Yes. Depending on the company, applicable laws and transaction circumstances, potential liquidity routes can include secondary sales, buybacks, strategic transactions, share swaps, acquisitions and financing against shares.
Why Is Liquidity Important in Unlisted Shares?
Unlike listed shares, unlisted securities do not trade continuously on a stock exchange. Investors may therefore find it difficult to sell immediately or at their desired price.
Final Thoughts
A reported ₹25,000 crore proposal involving Tata Sons naturally attracts attention.
But the number is not the most interesting part of the story.
The real lesson is this:
One of India’s Most Prominent Private-Company Shareholdings Is Demonstrating That Shareholder Liquidity and an IPO Are Two Different Things.
A company can remain unlisted while ownership changes.
A shareholder can monetise part of a stake without selling everything.
A private holding can support financing.
A buyback can potentially create liquidity.
A share swap can potentially transform an illiquid holding into more liquid securities.
And an IPO remains only one of several possible outcomes.
For investors in unlisted shares, understanding this distinction could ultimately be far more valuable than predicting the next IPO date.
Before the bell rings… Vault it!
Disclaimer
This article is intended solely for educational and informational purposes and should not be construed as investment advice, research, solicitation or a recommendation to buy, sell or hold any security.
VaultStreet Advisors is a boutique platform facilitating unlisted share transactions. We do not provide investment advisory services. All investments are subject to market risks. Please consult your financial advisor.
Information relating to Tata Sons, Shapoorji Pallonji Group, potential stake monetisation, possible buybacks, share swaps, regulatory status or IPO possibilities is based on publicly available information and media reports available as of 12 September 2026. Discussions, transaction structures, valuations and regulatory positions may change, and no proposed transaction should be considered completed unless formally announced by the relevant parties.
Unlisted and pre-IPO investments involve risks including valuation risk, liquidity risk, regulatory risk, transfer restrictions, information asymmetry, IPO delays or cancellations and potential loss of capital.