

For years, one company occupied an unusual position in India’s unlisted share market.
National Stock Exchange of India Limited — NSE.
It was unlisted, but hardly unknown.
It had the scale of a major listed company, extensive financial information, an established business model, a listed competitor in BSE for comparison and enormous investor interest.
The numbers show just how extraordinary that journey became.
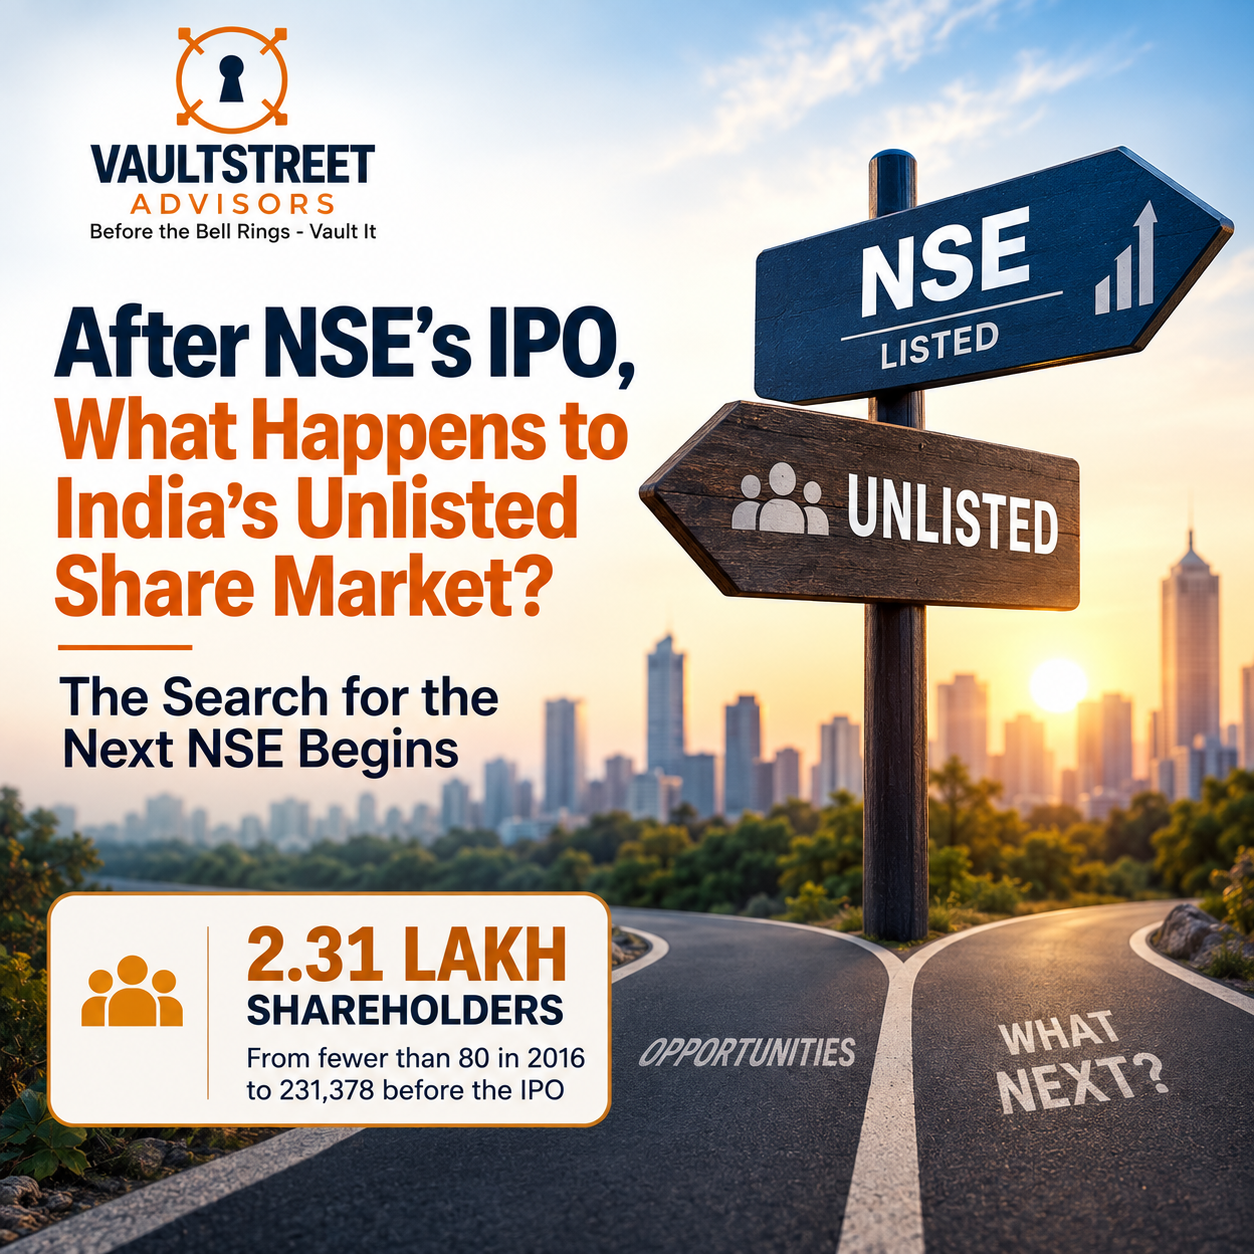
NSE reportedly had fewer than 80 shareholders in 2016.
Ahead of its 2026 IPO, that number had expanded to approximately:
231,378 shareholders.
And in NSE’s last disclosed monthly share-transfer data, nearly ₹1,500 crore worth of shares changed hands in March 2025 alone.
NSE didn’t merely become one of India’s most popular unlisted shares.
It helped transform unlisted-share investing from a relatively niche activity into a much broader market involving individual investors, HNIs, family offices, wealth managers, brokers and specialised platforms.
Now NSE is preparing to leave that market.
Its IPO is scheduled to open on 17 September 2026, with a price band of ₹1,700–₹1,785 per share.
Riddhi Siddhi Share Brokers has separately analysed the public-market side of the issue in NSE IPO Price Band ₹1,700–₹1,785: Should You Apply? Valuation, Lot Size, Dates & Key Risks Explained.
But for India’s unlisted market, NSE’s IPO raises a much bigger question:
What happens to India’s unlisted share market after NSE becomes listed?
And perhaps the question many investors will inevitably ask:
Where is the next NSE?
At VaultStreet Advisors, we believe that may actually be the wrong question.
The better question is:
Where are the good businesses available at sensible valuations?
NSE Wasn’t Just Another Unlisted Share
To understand what may happen next, investors first need to understand why NSE became so unusual.
Most companies trading in India’s unlisted market face one or more limitations:
- relatively limited financial information;
- lower transaction liquidity;
- difficulty establishing reliable valuation benchmarks;
- uncertainty around an eventual IPO;
- limited public familiarity; or
- significant differences between prices quoted by different market participants.
NSE was different.
It combined several characteristics rarely available together in an unlisted company:
Scale + profitability + brand recognition + financial disclosure + a listed comparable + liquidity + eventual IPO visibility.
Its smaller listed rival, BSE, also provided investors with something extremely valuable: a continuously traded public-market benchmark.
We recently examined this relationship in detail in NSE vs BSE: One Has Nearly 2× the Listed Companies. The Other Makes 4× the Profit.
The comparison illustrates something important about NSE.
It wasn’t merely a company waiting for an IPO.
It was already one of India’s most important pieces of financial-market infrastructure.
That combination helped make NSE almost a category of its own.
NSE Helped Build an Entire Unlisted-Share Ecosystem
Consider the shareholder expansion again:
2016: fewer than 80 shareholders
Before the 2026 IPO: approximately 231,378 shareholders
That transformation is remarkable.
Over the years, investors wanting exposure to NSE before its listing had to acquire shares through permitted off-market transactions.
As demand increased, an ecosystem developed around those transactions.
This included:
- specialised unlisted-share platforms;
- intermediaries;
- HNIs;
- family offices;
- wealth managers;
- individual investors; and
- buyers and sellers seeking off-market liquidity.
Recent market commentary has estimated that NSE accounted for a substantial proportion of activity in India’s unlisted-share ecosystem.
If those estimates are directionally correct, NSE’s departure represents much more than one company completing an IPO.
One of the biggest liquidity magnets in India’s unlisted ecosystem is moving into the listed market.
And that could reshape the industry.
This transition is particularly interesting because it comes at a time when India’s IPO and unlisted markets are already moving differently.
We examined that divergence recently in IPO Boom, Unlisted Slowdown: What India’s ₹70,000 Crore September Rush Means for Pre-IPO Investors.
What Happens When NSE Disappears From the Unlisted Market?
The immediate assumption may be that investors will simply move their money into another popular pre-IPO company.
Reality is likely to be more complicated.
There is currently no obvious company combining all the characteristics that made NSE unusual.
A company may have an exciting industry but limited disclosure.
Another may have strong financials but very little liquidity.
Another may have IPO ambitions but already trade at an aggressive valuation.
And another may have an attractive business but no clear timeline for providing liquidity to shareholders.
That means the post-NSE unlisted market could become:
More Fragmented
Instead of one dominant name absorbing a disproportionate amount of investor attention, capital could spread across multiple businesses and industries.
More Selective
Investors may need to perform substantially more company-specific due diligence.
More Valuation-Sensitive
Without NSE’s unusual combination of familiarity and liquidity, investors may become more conscious of the premium they are paying for IPO expectations.
And potentially:
More Opportunity-Driven Rather Than Company-Driven
Investors may increasingly search across sectors rather than repeatedly concentrating around one dominant pre-IPO story.
Where Could Unlisted-Market Attention Move Next?
Recent market commentary suggests investor attention is already broadening towards sectors such as:
- space technology;
- aerospace;
- defence;
- data centres;
- advanced manufacturing;
- financial services; and
- other new-age industries.
But this is where investors need to be particularly careful.
A sector becoming fashionable does not automatically make every unlisted company in that sector attractive.
Artificial intelligence, defence, aerospace, data centres and advanced manufacturing may all offer significant long-term business opportunities.
For example, we recently examined the data-centre theme through Yotta at $3.9 Billion Before IPO: Is India’s AI Data Centre Boom Creating the Next Big Pre-IPO Opportunity?.
But investors are not purchasing industries.
They are purchasing ownership in specific companies at specific valuations.
That distinction is critical.
Don’t Search for the Next NSE
Whenever an investment generates extraordinary attention, markets naturally start searching for its successor.
The next NSE.
The next multibagger.
The next blockbuster IPO.
The next company capable of creating enormous pre-listing wealth.
But there is a problem with this thinking.
The search itself can inflate valuations.
Once a company begins being described as the “next big pre-IPO opportunity”, demand can increase rapidly.
Supply of unlisted shares may remain limited.
Quoted prices rise.
More investors notice the price movement.
That attracts additional demand.
And gradually the valuation may begin reflecting not merely the company’s present business but increasingly optimistic expectations about its future IPO.
We discussed precisely these dangers in Pre-IPO Doesn’t Always Mean Pre-Profit: 7 Risks Investors Ignore When Buying Unlisted Shares.
Another fascinating example is the Calcutta Stock Exchange unlisted-share rally from approximately ₹900 to ₹2,100, where market expectations surrounding a potential revival became an important part of the valuation story.
The broader lesson is simple:
Expectations can move faster than fundamentals.
And NSE itself is now providing an excellent real-world example of why entry valuation matters.
NSE’s ₹1,826.85 Investor Offers an Important Lesson
NSE’s IPO price band has been fixed at:
₹1,700–₹1,785 per share.
Yet NSE’s offer documents provide an interesting example.
One shareholder participating in the offering reportedly acquired 500 NSE shares at ₹1,826.85 per share.
At the IPO upper band of ₹1,785, that is approximately ₹41.85 per share below the investor’s acquisition price, or around 2.3% lower.
The example does not tell us what NSE will trade at after listing.
Nor does it establish the eventual return earned by that shareholder.
But it illustrates something every pre-IPO investor should understand:
Buying before the IPO does not guarantee buying below the IPO price.
We explored precisely this issue in Bought NSE Unlisted Shares Above ₹2,000? What the ₹1,785 IPO Price Could Mean for Investors.
The public-market perspective is equally useful. Riddhi Siddhi Share Brokers’ detailed NSE IPO analysis examines the ₹1,700–₹1,785 price band, valuation, OFS structure and key risks from the perspective of investors evaluating the IPO itself.
Together, the unlisted-market and IPO perspectives highlight one crucial principle:
A great company can still become an unattractive investment if the entry valuation already assumes too much future success.
The Post-NSE Market Could Actually Become Healthier
NSE leaving the unlisted market may initially reduce activity.
But over the longer term, there is another possibility worth considering.
India’s unlisted market may become less dependent on one company.
That could encourage investors to analyse businesses more fundamentally.
Instead of asking:
“Which share is everybody buying?”
Investors may increasingly ask:
“What exactly am I buying — and at what valuation?”
That means examining:
Business Quality
What does the company actually do, and does it possess a sustainable competitive advantage?
Financial Performance
Are revenue, profitability and cash flows improving?
Valuation
What market capitalisation is implied by the unlisted share price?
Listed Comparables
Are similar publicly traded companies available at lower valuations?
Liquidity
How easily can an investor eventually find a buyer?
Information Availability
Are audited financial statements and other important disclosures readily available?
IPO Visibility
Has the company actually taken identifiable steps towards listing, or is the IPO merely market speculation?
Exit Risk
What happens if the expected IPO takes three years, five years — or never happens?
These questions matter far more than whether a company is being called the “next NSE.”
Liquidity May Become the Biggest Differentiator
NSE’s enormous shareholder base and transaction activity created something unusual for an unlisted company:
Relatively deep investor participation.
That should not be assumed for other unlisted securities.
An investor may see a quoted price and conclude that the shares are worth that amount.
But a quoted price is not necessarily equivalent to a liquid market.
A better question is:
If I needed to sell a meaningful quantity tomorrow, how many genuine buyers would exist at approximately this price?
In listed markets, investors can observe bids, offers, volumes and market depth.
In unlisted markets, transactions are negotiated privately.
That makes liquidity analysis particularly important.
The increasing interest from professional capital also makes this evolution worth watching. Our analysis of JM Financial’s ₹700 Crore Pre-IPO Fund explains what growing institutional participation may signal for India’s unlisted and pre-IPO market.
The presence of institutional capital, however, does not eliminate liquidity or valuation risk for individual investors.
The Next Phase Could Be About Themes, Not One Superstar
NSE’s journey was difficult to replicate because several favourable factors came together simultaneously.
The next phase of India’s unlisted market may therefore look very different.
Instead of one enormous dominant opportunity, investor interest could rotate across multiple structural themes.
Defence & Aerospace
India’s growing defence manufacturing and localisation ambitions have increased attention on private companies participating in the ecosystem.
Data Centres & Digital Infrastructure
AI adoption, cloud computing and rising digital consumption are creating significant infrastructure requirements.
Financial Infrastructure
Exchanges, market-infrastructure institutions, fintech businesses and financial-services platforms continue to attract investor attention.
Advanced Manufacturing
Supply-chain diversification and domestic manufacturing expansion are creating interest across electronics, industrial components and specialised engineering.
But investors should remember:
A powerful theme cannot rescue an excessive valuation.
The Most Important Question Is Not “Will It IPO?”
For many investors entering the pre-IPO market, the first question is:
When will the IPO happen?
It is understandable.
An IPO can create liquidity and public price discovery.
But the question investors should ask before that is:
Would I still want to own this business if the IPO were delayed by three years?
That simple question changes the investment framework.
If the entire thesis depends on somebody paying a higher price immediately after an IPO, the investor may be speculating primarily on an event.
If the thesis instead rests on:
- business growth;
- earnings growth;
- competitive advantages;
- sensible valuation;
- improving cash flows; and
- long-term industry opportunity,
then an IPO becomes a potential liquidity event rather than the sole reason for owning the shares.
That distinction matters enormously.
Five Questions Before Looking for the “Next NSE”
Before buying an unlisted share simply because it is gaining market attention, investors can ask five questions.
1. What Is the Implied Market Capitalisation?
Never evaluate an unlisted company merely by its per-share price.
Understand the number of outstanding shares and calculate what valuation the quoted price implies.
2. What Do the Financials Support?
Study revenue, profitability, debt, cash flows, return ratios and historical growth wherever reliable information is available.
3. What Are Comparable Listed Companies Worth?
A company being unlisted does not automatically justify a valuation premium.
Listed peers may sometimes provide better liquidity and transparency at comparable or even lower valuations.
4. How Real Is the IPO Timeline?
Separate formal IPO progress from market rumours.
DRHP filings, banker appointments, shareholder approvals and regulatory developments carry more weight than informal market chatter.
5. What Happens If the IPO Doesn’t Come Soon?
Investors should be financially and psychologically prepared for illiquidity.
An unlisted share should not be treated like a listed security simply because an intermediary is currently quoting a price.
From Fewer Than 80 Shareholders to 2.31 Lakh: NSE’s Real Legacy
NSE’s IPO will understandably generate enormous attention.
But its biggest impact on India’s unlisted market may have occurred before the IPO itself.
The exchange went from fewer than 80 shareholders in 2016 to more than 2.31 lakh shareholders before its public offering.
In the process, it introduced a much wider set of investors to the idea of owning shares in a company before listing.
Platforms developed.
Liquidity increased.
Information became easier to access.
More investors began studying pre-IPO businesses.
And India’s unlisted market became significantly more visible.
NSE will now graduate from that ecosystem.
The ecosystem itself is unlikely to disappear.
But it may have to evolve.
VaultStreet Advisors View: Don’t Find the Next NSE. Find the Right Valuation.
The temptation after NSE’s listing will be obvious.
Investors, intermediaries and platforms will search for another company capable of generating the same excitement.
We believe investors should resist that framing.
Don’t search for the next NSE.
Search for the next good business available at the right valuation.
That means looking beyond IPO excitement.
Study the business.
Understand the financials.
Calculate the valuation.
Assess liquidity.
Examine available disclosures.
Understand the sector.
Question the IPO assumptions.
And most importantly:
Know the price you are paying for the future you are expecting.
NSE’s journey demonstrates how powerful pre-IPO investing can become when business quality, investor interest and liquidity come together.
Its IPO also demonstrates the other side of that equation:
Being early is valuable only when you are not paying tomorrow’s valuation today.
That may ultimately be NSE’s most important lesson for India’s next generation of unlisted-share investors.
Explore Unlisted & Pre-IPO Opportunities
To understand and explore India’s unlisted and pre-IPO market, visit VaultStreet Advisors.
📲 Message +91 99875 53455 to request access to our exclusive WhatsApp community for daily prices, opportunities and market updates.
For investors interested in listed equities, derivatives, mutual funds, IPOs, SLBM and Assisted Trading Services, explore the Riddhi Siddhi Share Brokers Services page.
VaultStreet Advisors
Before the bell rings… Vault it!
Frequently Asked Questions
What happens to NSE unlisted shares after the IPO?
Once NSE completes its listing, its shares transition from the unlisted/off-market ecosystem to publicly traded shares, subject to applicable listing, settlement and lock-in provisions for different categories of shareholders.
Will NSE’s IPO reduce India’s unlisted-share market?
NSE has historically represented an unusually important part of India’s unlisted market. Its departure could affect activity in the short term, but investor interest may redistribute across other companies and sectors.
The eventual impact will depend on new companies entering the pre-IPO ecosystem, valuations, liquidity and India’s broader IPO pipeline.
Which company could become the next NSE in the unlisted market?
There is no reliable way to identify a “next NSE.”
NSE had an unusual combination of scale, profitability, disclosure, brand recognition, liquidity, network effects and a listed comparable.
Investors should therefore evaluate individual companies on their own fundamentals and valuations rather than attempt to find a direct replacement.
Are unlisted shares always cheaper before an IPO?
No.
An unlisted-market price can be above or below the eventual IPO price.
NSE provides a current example: its IPO upper price band is ₹1,785 even though shares have changed hands privately at higher prices.
This principle and other risks are explained in greater detail in our 7 Risks Investors Ignore When Buying Unlisted Shares guide.
What should investors check before buying unlisted shares?
Important factors include:
- the company’s business model;
- audited financials;
- implied valuation;
- listed-company comparables;
- liquidity;
- shareholder structure;
- available disclosures;
- regulatory risks;
- IPO visibility; and
- the investor’s ability to tolerate an uncertain exit period.
Disclaimer
VaultStreet Advisors is a boutique platform facilitating unlisted share transactions. We do not provide investment advisory services. All investments are subject to market risks. Please consult your financial advisor.
This article is intended solely for educational and informational purposes and does not constitute investment advice, a recommendation, solicitation or an offer to buy or sell any security.
References to NSE, BSE, Calcutta Stock Exchange, Yotta or any other company or sector are included solely for educational purposes and to explain developments in India’s unlisted and pre-IPO market. They should not be interpreted as recommendations to buy, sell or hold any security.
Unlisted and pre-IPO securities involve significant risks, including liquidity risk, valuation risk, information asymmetry, regulatory uncertainty and uncertainty regarding eventual listing or exit.
An IPO is not guaranteed, and buying shares before an IPO does not guarantee profits or a favourable listing price.
Financial figures, transaction data, IPO information and other information referenced in this article are based on publicly available information considered reliable at the time of publication. Investors should independently verify current information and consult an appropriately qualified financial adviser before making investment decisions.