

Maverick Simulation Solutions Limited has suddenly become an interesting name in India’s unlisted-share market.
The reason is bigger than a movement in its indicative unlisted share price.
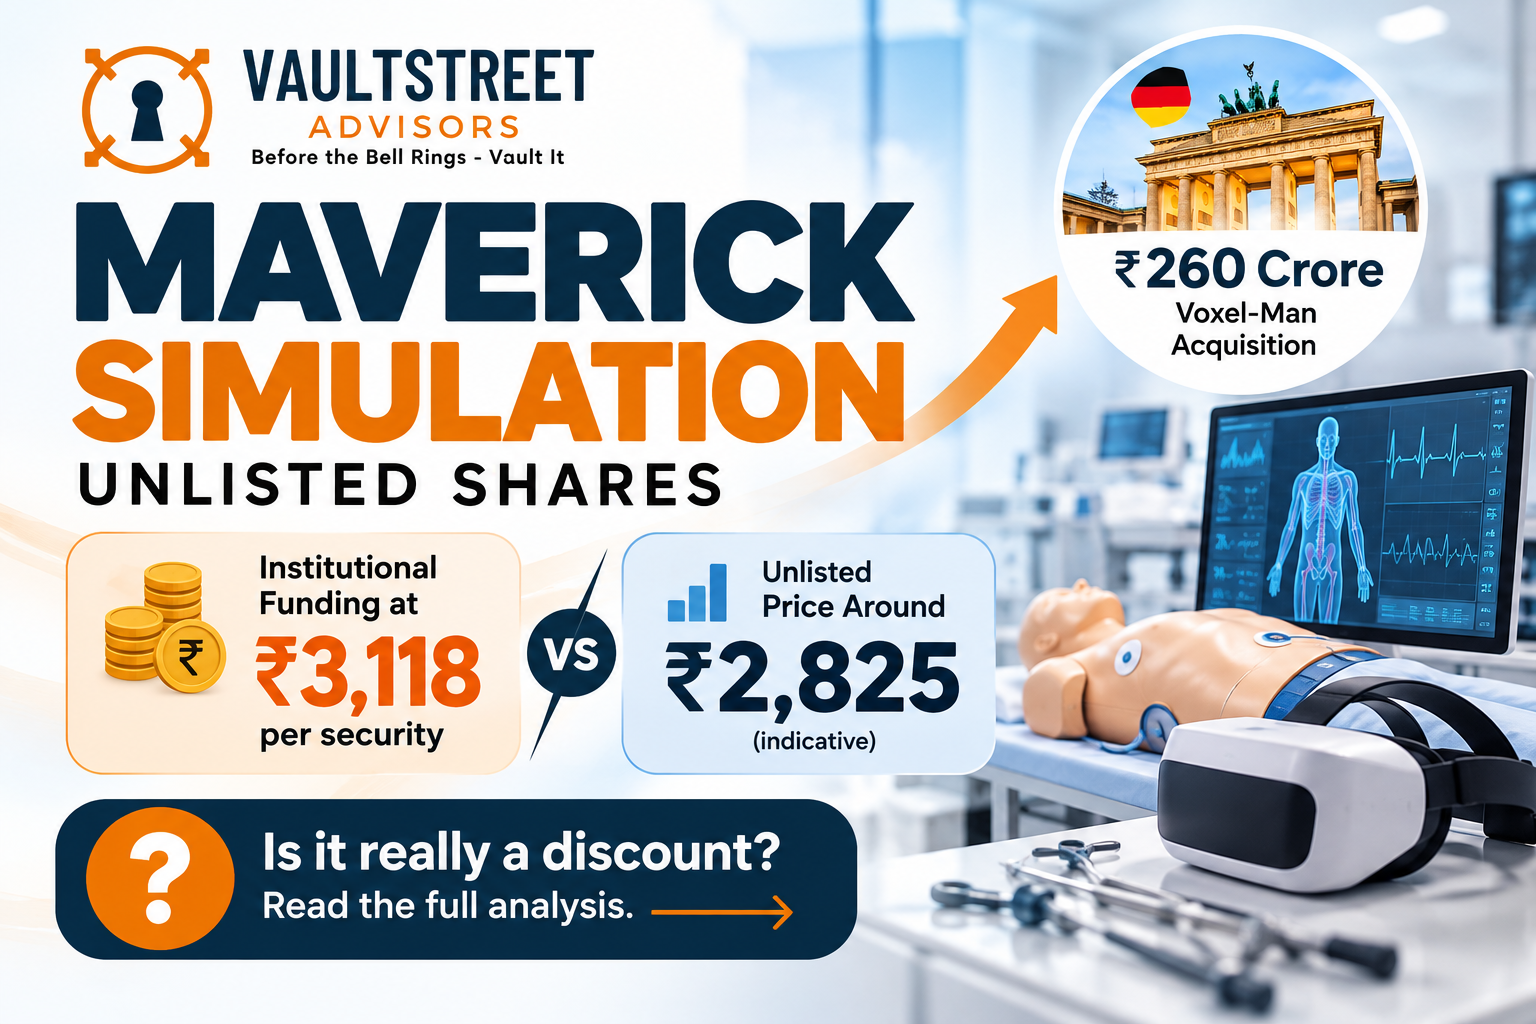
Maverick has proposed raising approximately ₹125.5 crore from institutional investors at ₹3,118 per security, predominantly through Series-B Compulsorily Convertible Preference Shares (CCPS).
At the same time, the company is pursuing the acquisition of Voxel-Man GmbH, a Germany-based medical simulation technology company, in a transaction valued at approximately ₹260 crore, with the consideration proposed through Maverick shares rather than cash.
Meanwhile, recent secondary-market references for Maverick Simulation ordinary equity have appeared below the ₹3,118 institutional transaction price.
That creates an obvious question:
If institutions are investing at ₹3,118, are Maverick Simulation unlisted shares available at a discount in the secondary market?
The answer is:
Not necessarily.
The numbers may look directly comparable.
The underlying securities and transaction terms may not be.
And that distinction is far more important than the apparent price gap.
Maverick Simulation Unlisted Share Price: Latest Position
Maverick Simulation Solutions is currently an unlisted company.
Its shares therefore do not trade on an NSE/BSE-style continuous exchange order book.
Recent secondary-market references have varied across unlisted-market platforms. One market reference indicated approximately ₹2,825 per share on October 6, 2026, while another tracker showed approximately ₹2,913.75 on October 5, 2026.
These numbers should therefore be treated as indicative secondary-market references, not as one official Maverick Simulation market price.
This distinction matters.
As VaultStreet Advisors explains in its guide to 25 important unlisted-share market terms, quotations from different market participants can vary because there is no central exchange order book continuously establishing one universally observable price.
Price can also depend on available quantity, demand, supply, transaction size, liquidity and settlement terms.
A quoted unlisted price is not necessarily an official market price or a guaranteed executable price.
What Does Maverick Simulation Solutions Do?
Maverick Simulation Solutions operates in the medical simulation and healthcare-training technology segment.
Its business includes simulation products and technologies intended to help healthcare professionals and students practise clinical procedures in controlled environments.
The broader product portfolio includes medical and surgical simulation systems, patient simulators, task trainers, virtual anatomy and other healthcare-training technologies.
That places Maverick within a specialised intersection of:
Healthcare + Medical Education + Simulation + Technology
For investors researching Maverick Simulation unlisted shares, understanding the underlying business is more important than simply tracking a changing secondary-market quotation.
What Is Maverick Simulation’s ₹125.5 Crore Institutional Fundraise?
The proposed institutional transaction involves the issuance of approximately:
4,02,486 Series-B CCPS
plus
10 equity shares
at an issue price of:
₹3,118 per security
The reported issue price comprises a face value of ₹10 and securities premium of ₹3,108.
The aggregate proposed fundraise is approximately:
₹125.5 crore.
The proposed institutional investors include:
| Investor | Approximate Investment |
|---|---|
| Paragon Partners Growth Fund II | ₹75 crore |
| VantEdge Partners LLP | ₹38.5 crore |
| Inviga Healthcare Fund I | ₹12 crore |
| Total | ₹125.5 crore |
The transaction is important because it provides investors with a fresh institutional valuation reference.
But it does not automatically establish ₹3,118 as the fair value of every Maverick security.
That distinction is crucial.
₹3,118 Institutional Price vs Secondary-Market Equity: Is Maverick Really Trading at a Discount?
This is the most important question in the entire Maverick Simulation story.
Take the lower recent indicative secondary-market reference of approximately ₹2,825.
Compare it with the institutional issue price of:
₹3,118.
The numerical difference is:
₹3,118 − ₹2,825 = ₹293
That works out to approximately:
10.4%.
At first glance, an investor could therefore conclude:
“Institutions are investing at ₹3,118 while Maverick equity is being quoted around ₹2,825. So I am getting approximately a 10% discount.”
That conclusion would be too simplistic.
₹3,118 and ₹2,825 do not automatically represent economically identical securities acquired on identical terms.
This is exactly where investors need to look beyond the headline price.
Maverick Equity vs Series-B CCPS: Why the Difference Matters
Most of the proposed institutional investment is through:
Series-B Compulsorily Convertible Preference Shares.
CCPS are not automatically identical to ordinary equity shares simply because they may eventually convert into equity.
Depending upon their contractual terms, preference securities can carry rights and protections that ordinary equity shareholders may not possess.
These may relate to matters such as:
- conversion;
- preferential rights;
- seniority;
- anti-dilution protection;
- liquidation economics;
- governance rights; and
- other negotiated investor protections.
The exact rights applicable to Maverick’s Series-B CCPS should therefore be assessed from the underlying transaction documents rather than assumed.
This is the same principle VaultStreet Advisors recently highlighted while analysing Zepto Equity vs CCPS.
A differently priced Equity share and CCPS cannot simply be placed side by side and labelled “cheap” or “expensive”.
Compare the security—not merely the company name and price.
Before comparing an institutional transaction with a secondary-market quotation, investors should understand:
- Security class
- Conversion ratio
- Conversion conditions
- Preferential rights
- Seniority
- Anti-dilution provisions
- Transfer restrictions
- Resulting fully diluted ownership
A lower ordinary-equity quotation does not automatically mean that a secondary-market investor is receiving a better deal than an institutional investor.
Why Can Maverick Simulation Unlisted Share Prices Differ Across Platforms?
This is another important lesson for investors researching Maverick Simulation unlisted shares.
Unlike a listed security, there is generally no continuously operating public order book showing every buyer and seller of an unlisted share.
Consequently, two market participants can quote different prices for the same unlisted security.
Prices can vary depending on:
- available quantity;
- minimum lot;
- buyer demand;
- seller expectations;
- intermediary;
- liquidity;
- transaction size; and
- settlement terms.
That is why an investor may encounter different Maverick Simulation unlisted share prices on different platforms.
VaultStreet Advisors explains this distinction in detail in its unlisted-share market terminology guide.
An indicative quotation provides useful market information.
It is not an exchange-discovered price, guaranteed transaction price or guaranteed exit value.
Maverick Financials: FY25 Shows Sharp Growth
Maverick’s reported financial performance has also attracted attention.
Available financial information indicates FY25 revenue of approximately:
₹136.3 crore
compared with roughly:
₹14.2 crore in FY24.
Reported profit after tax increased from approximately:
₹0.95 crore
to approximately:
₹47.8 crore.
Those headline numbers represent very strong year-on-year growth.
But investors should be careful about extrapolating a single period of rapid expansion indefinitely.
The better questions are:
How sustainable is the revenue?
Can margins be maintained?
How much operating cash flow does the business generate?
How will acquisitions affect future earnings?
What happens to the fully diluted share count?
Can Maverick continue scaling without materially weakening return ratios?
Rapid historical growth is important.
Sustainable growth is more important.
What Is Maverick’s ₹260 Crore Voxel-Man Acquisition?
Alongside the institutional fundraising, Maverick is pursuing the acquisition of 100% of Voxel-Man GmbH.
The reported transaction consideration is approximately:
₹260 crore.
Voxel-Man specialises in virtual medical and surgical simulation technology.
The transaction is proposed to be completed using Maverick shares rather than cash, with approximately 8.34 lakh Maverick equity shares reportedly forming the consideration based on the ₹3,118 reference price.
Strategically, the acquisition could broaden Maverick’s technological capabilities and international exposure in advanced healthcare simulation.
But acquisitions should never be evaluated only from the strategic narrative.
Investors should subsequently monitor several things.
Integration
Can Maverick successfully integrate Voxel-Man’s technology, products and operations?
Financial Contribution
How much revenue and profitability could Voxel-Man ultimately contribute?
Acquisition Valuation
Was approximately ₹260 crore an economically attractive price for Maverick shareholders?
Dilution
Because shares are proposed as consideration, investors should understand the effect on Maverick’s fully diluted capital structure.
Governance and Disclosures
The transaction documents, approvals, ownership relationships and governance arrangements should be evaluated carefully rather than relying only on the headline acquisition value.
What Valuation Does the ₹3,118 Institutional Price Imply?
A share price alone does not tell an investor whether a company is cheap or expensive.
The better question is:
What overall company valuation does ₹3,118 imply?
Available transaction analysis has placed the proposed institutional round at an implied valuation of roughly ₹1,545 crore pre-money and ₹1,671 crore post-money, depending on the capital-structure and dilution assumptions used.
These should be understood as transaction-implied valuation estimates, not as an official exchange market capitalisation.
Maverick remains unlisted.
There is no continuously traded public market independently establishing its market capitalisation every day.
This is why investors should look beyond the per-share number.
Consider:
- outstanding shares;
- fully diluted shares;
- revenue;
- earnings;
- operating cash flow;
- debt;
- margins;
- growth;
- acquisition impact;
- comparable companies; and
- liquidity.
A ₹3,000 share is not automatically expensive.
A ₹300 share is not automatically cheap.
Price and valuation are different concepts.
Does Institutional Investment Mean Maverick Is Undervalued?
No.
Institutional participation can be an important validation point for a business.
But it does not prove that the investment will generate returns.
Institutional investors may negotiate terms unavailable to ordinary secondary-market investors.
Their:
- security rights;
- investment horizon;
- information access;
- governance arrangements;
- downside protections;
- portfolio strategy; and
- liquidity expectations
can differ substantially from those of an individual investor purchasing existing equity.
Therefore:
“Institutions invested” is information. It is not an investment thesis by itself.
A better set of questions is:
What valuation did institutions invest at?
What security did they receive?
What rights came with it?
How much dilution will occur?
What assumptions about future growth support the valuation?
And what could still go wrong?
This is consistent with the broader principle discussed in VaultStreet Advisors’ guide to 7 risks investors should understand before buying pre-IPO and unlisted shares.
Getting in before an IPO does not automatically mean getting in cheap.
What Should Maverick Simulation Unlisted Shareholders Monitor Next?
For existing shareholders and investors researching Maverick Simulation, several developments deserve attention.
1. Completion of the Institutional Round
Investors should monitor completion of the Series-B transaction and the resulting capital structure.
2. Voxel-Man Acquisition
The acquisition’s completion, integration and subsequent financial contribution will be important.
3. FY26 and Future Financial Performance
The key question is whether Maverick can sustain the sharp expansion visible in its recent reported numbers.
4. Cash Generation
Strong reported profitability becomes considerably more meaningful when supported by sustainable operating cash flows.
5. Dilution
New securities and acquisition consideration can affect the fully diluted share count and therefore each existing shareholder’s economic ownership.
6. Secondary-Market Price
Investors should monitor price together with the valuation it implies rather than looking at the per-share quotation in isolation.
7. IPO Developments
Institutional fundraising does not guarantee an IPO.
Any future Maverick Simulation IPO timeline should be evaluated only when supported by credible company or regulatory disclosures.
The VaultStreet View
The Maverick Simulation story is interesting for a reason bigger than a ₹125.5 crore fundraising headline.
It provides a useful real-world lesson in how private-market pricing works.
An institutional transaction has created a fresh ₹3,118 reference price.
Recent secondary-market equity indications have appeared below that level.
But the correct conclusion is not:
“Maverick is available at a 10% discount.”
The more accurate conclusion is:
Understand exactly what security each price represents before comparing the two.
That is the difference between simply looking at an unlisted share price and properly evaluating an unlisted investment.
At VaultStreet Advisors, we believe investors should examine the business, financials, security structure, valuation, liquidity and transaction terms together rather than treating one headline price as proof that a share is cheap or expensive.
Frequently Asked Questions
What is the Maverick Simulation unlisted share price?
Maverick Simulation Solutions is unlisted, so there is no official NSE/BSE-style continuously traded market price. Recent secondary-market references have varied, including approximately ₹2,825 on October 6, 2026 and approximately ₹2,913.75 on October 5, 2026. Actual availability and executable prices can vary according to quantity, demand, supply, liquidity and transaction terms.
At what price are institutions investing in Maverick Simulation?
The proposed Series-B institutional transaction has been reported at ₹3,118 per security, with approximately ₹125.5 crore proposed to be raised predominantly through Series-B CCPS.
Does ₹3,118 mean Maverick Simulation is worth ₹3,118 per ordinary equity share?
Not automatically. Most of the proposed institutional investment involves Series-B CCPS. Investors need to understand the security’s conversion and contractual rights before comparing its transaction price directly with ordinary secondary-market equity.
Is Maverick trading at a 10% discount to the institutional price?
That conclusion would be misleading. The numerical difference between ₹3,118 and a ₹2,825 secondary-market reference is approximately 10.4%, but the two figures may represent different securities and transaction terms. It should not automatically be treated as a discount or arbitrage opportunity.
What does CCPS mean?
CCPS stands for Compulsorily Convertible Preference Shares. These securities convert into equity according to specified contractual terms and may carry rights different from ordinary equity shares.
Why do different websites show different Maverick Simulation share prices?
Unlisted shares do not have the same continuously visible central exchange order book as NSE/BSE-listed shares. Different participants may therefore quote different prices depending on quantity, availability, liquidity, demand, supply and transaction terms.
Is Maverick Simulation planning an IPO?
Investors should distinguish between institutional fundraising and a formally documented IPO process. Unless supported by official company or regulatory filings, the timing of any future Maverick Simulation IPO should be treated as uncertain.
Is Maverick Simulation an unlisted company?
Yes. Maverick Simulation Solutions Limited is currently an unlisted company, so its shares do not trade through a normal NSE/BSE continuous public order book.
Connect With VaultStreet Advisors
For current indicative availability, transaction details and market information on Maverick Simulation Solutions and other unlisted or pre-IPO shares, connect with VaultStreet Advisors.
Website: www.vaultstreet.in
Unlisted Share Enquiries: +91 91379 69859
Message +91 99875 53455 to request access to our exclusive WhatsApp community for daily prices, opportunities and market updates.
For investors looking for execution support in the listed market, connect with Riddhi Siddhi Share Brokers for Assisted Trading Services.
Explore Assisted Trading & Other Services at Riddhi Siddhi Share Brokers
Before the bell rings… Vault it!
Disclaimer
VaultStreet Advisors LLP is a boutique platform focused on facilitating unlisted share transactions. We do not provide investment advisory services or portfolio recommendations. All investments are subject to market risks. Please consult your financial advisor before investing.
This article is for educational and informational purposes only and does not constitute investment advice, a stock recommendation, an offer or a solicitation to buy, sell or hold any security.
Unlisted-market prices mentioned in this article are indicative third-party market references and should not be considered official exchange prices, guaranteed quotes, fair values or guaranteed exit prices. Prices and availability can change without notice.
Unlisted and pre-IPO securities involve risks including limited liquidity, price-discovery risk, valuation uncertainty, dilution, transfer restrictions, information asymmetry and uncertainty regarding future IPO or exit timelines.
Investors should independently verify the company, exact security class, ISIN, conversion terms where applicable, contractual rights, financial information, valuation, transfer conditions and applicable regulations before entering any transaction.